by
When analyzing a real estate investment opportunity, there are many financial indicators, but few are as critical for assessing risk as the Loan-to-Value (LTV) ratio. If you’re just starting to build your real estate portfolio, understanding this metric is the first step toward making informed decisions and assessing the margin of safety for your investments.
At wecity, the LTV is one of the non-negotiable criteria used by our investment committee before publishing any opportunity. Below, we explain in simple terms what it means, how to interpret it, and why we look for conservative percentages.
What Is Loan-to-Value (LTV)?
Loan-to-Value (LTV) is a financial ratio that measures the percentage relationship between the amount of the loan granted and the official, independent appraised value of the mortgaged property.
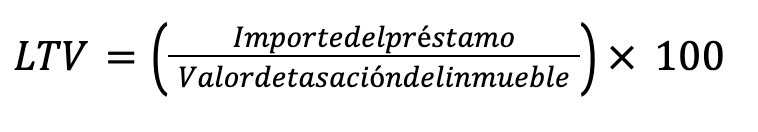
Key point: The LTV does not measure equity or the funds the developer has contributed. The purchase price agreed upon by the parties may differ from the officially approved appraised value. What the LTV objectively indicates is the cushion or coverage margin that the loan has relative to the appraised market value of the asset: the lower the LTV, the greater a decline in value the property could absorb in a potential judicial auction before the repayment of the debt is jeopardized.
Practical Example: How to Interpret the Coverage Margin
To understand how this works in practice, let’s look at a common example:
LTV calculation: $(500,000\text{ €} \,/\, 1,000,000\text{ €}) \times 100 = \mathbf{50\,\%}$.
Official appraised value of the asset (appraiser approved by the Bank of Spain): 1,000,000 € (regardless of whether the developer acquired it for a different amount, for example, 800,000 €).
Loan financed through wecity: 500,000 €.
What does this 50% mean for the investor?
This means that the loan amount represents only half of the appraised value of the property. If the developer were to default on the loan and it became necessary to initiate a first-lien foreclosure, the asset would have a theoretical depreciation margin of 50% before the auction sale price would fall below the outstanding debt.
Risk Warning: However, a low LTV does not eliminate the risk of loss or guarantee the full recovery of principal. In the event of a severe market downturn, a lack of liquidity in judicial auctions, or costs arising from litigation, the final auction price could be lower than the accumulated debt, resulting in investors incurring a partial or total loss of their investment.
Why does a conservative LTV protect investors?
In alternative financing transactions, the property serves as mortgage collateral. If a project encounters serious complications and the developer is unable to repay the principal, the first-lien mortgage.
If the transaction’s LTV is low (for example, between 50% and 65%), it means that, should it become necessary to foreclose on the collateral and liquidate the asset, there is ample room to sell the property—even at a price below its initial appraisal—and still obtain sufficient capital to repay the debt to investors.
Does a low LTV guarantee that there will be no losses?
It is crucial to understand that no financial metric, no matter how conservative, can completely eliminate risk. An LTV of 50% or 40% significantly mitigates the impact of a decline in real estate prices, but it does not absolutely guarantee the full recovery of principal.
Foreclosure proceedings take time, and if the market undergoes severe adjustments that drastically reduce the asset’s final sale value below the accumulated debt, a partial or total loss could occur. For this reason, the LTV should never be analyzed in isolation, but rather in conjunction with the developer’s creditworthiness and the project’s technical feasibility, among other factors.
Diversification: Your Second Line of Defense
Understanding LTV helps you select good projects, but the golden rule for protecting your wealth is not to concentrate all your capital in a single investment. At wecity, you can build a diversified portfolio by investing as little as €500 per project. Spreading your investment across several different opportunities with conservative LTVs is the smartest strategy for mitigating risk and stabilizing your returns over the medium term.
Would you like to start diversifying your portfolio with opportunities analyzed by our risk committee?
Check for risks: https://www.wecity.com/riesgos