

Description
wecity complies with the provisions of Regulation (EU) 2020/1503 of the European Parliament and of the Council of 7 October 2020 on European providers of participative financing services for companies and Title V of Law 5/2015 on the promotion of business financing as amended by Law 18/2022 of 28 September on the creation and growth of companies. It is authorized by the CNMV as a Participatory Financing Service Provider, registered under number 9, with a favorable proposal from the Bank of Spain.
Investor, before making your investment, please read the basic information for the investor client, as well as the pre-contractual cooling-off period for inexperienced investors .
Skin in the game: “In accordance with Article 8.2 of Regulation (EU) 2020/1503 of the European Parliament and of the Council of October 7, 2020, on European crowdfunding providers, we hereby inform you that partners, executives, and employees of wecity may invest in this offering. These investments will be made under the same conditions as those of other investors, without receiving preferential treatment or privileged access to information.”
The investment
- Purpose of the loan: Construction.
- Collateral:First-priority mortgage.
- Term: 11 months (+6-month extension possible)
- Maturity date: August 17, 2027
- Interest rate: 11.50% per annum.
- Estimated total return: 10.54%
- Interest payment: at maturity.
- Current ECO Appraisal: €3 ,315,451.23
- ECO HET Appraisal: 5.683.000€ | LTV: 48 . 57 %
- First Drawdown: €2 ,230,838 | LTV: 67 .28%
- Rating: A
- Contributions:
- Developer’s contribution: €1,544,468.66
- wecity Phase III Loan: €750,000
- Minimum investment: €500
- Maximum investment: €500 during the first ten minutes.
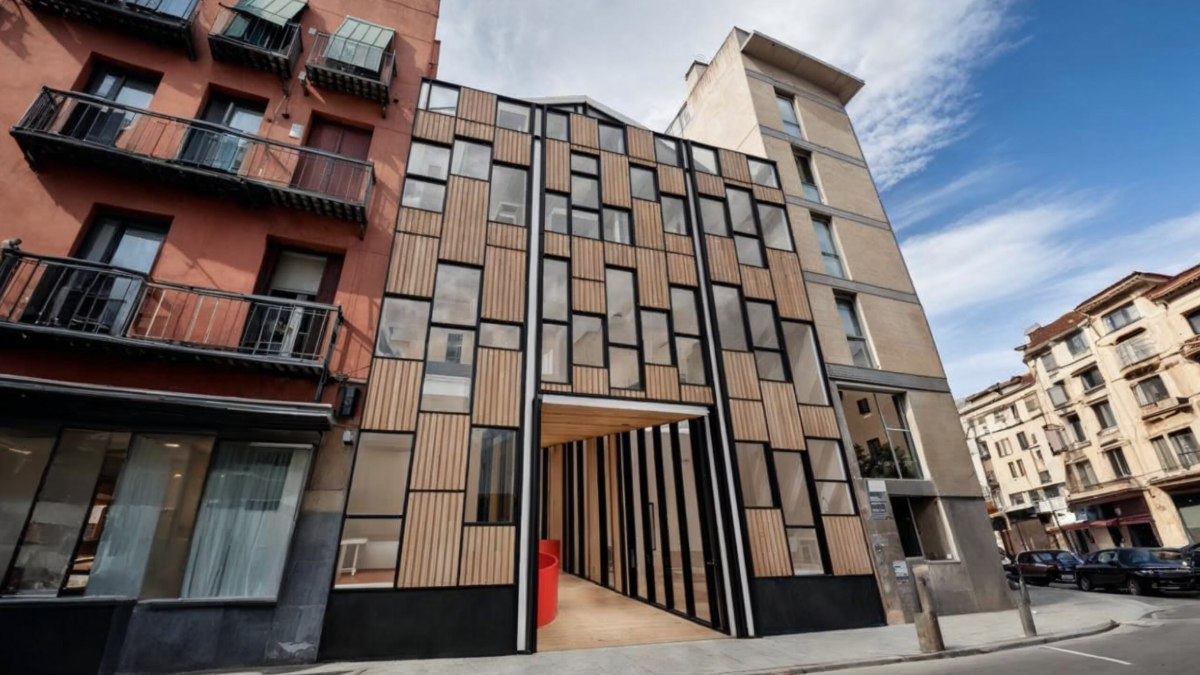
The development company IBERIA VIVA CAPITAL SL is requesting , through wecity, the activation of Phase III of the “Madrid, Juan de Olías” project to continue the renovation of a building located at 21 Juan de Olías Street in Madrid.
The building has a buildable area of 1,222.11m², where a mixed-use building is being renovated to create 20 lofts and 1 residential unit.
From an urban planning perspective, the project has held a building permit since September 2025, and construction has already begun, with progress currently at 73.04% (according to the latest certification issued by the project management team)1. The developer intends to retain the asset as part of its portfolio and operate it to generate rental income. From a commercial standpoint, the project has not generated any sales because the developer plans to retain the asset to generate returns.
The total amount of the loan to date is €2,750,000.00, disbursed in three phases. On this occasion, Phase III of the loan will be financed in the amount of €750,000 at a fixed rate; it will be secured by a first-lien mortgage on the asset and will have an estimated term of 11 months, maturing on August 17, 20273 (plus a possible 6-month extension).
To date, the developer has contributed €1 ,544,468 .66 in equity funds for the acquisition of the building and the commencement of construction.
Investors are expected to exit wecity once bank financing is secured and the asset begins to generate income.
AInvest
AInvest does not apply in this case.
Location and surroundings
Mortgage Collateral
The loan will be secured by afirst-lien mortgage on the property located at Calle de Juan de Olías, 21 (Madrid).
According to the appraisal report prepared by Tinsa, the Current Appraised Value is €3,315,451.23, and the Appraised Value on a Completed Building Basis (HET) is 5.683.000€. The loan to be granted to the developer in this third phase is 750,000 €, which represents a Loan-to-Value (LTV) ratio of 48.57% based on the Completed Building Valuation (HET) and an LTV ratio of 67.28% for the first drawdown.
Collateral Agent
The creation, maintenance, management, administration, and, where applicable, enforcement of the security interest on behalf of wecity investors will be handled by an entity external to wecity.
In this case, the designated Collateral Agent will be the one specified in the loan agreement.
Rating
wecity, as a provider of participatory financing services and in compliance with Delegated Regulation (EU) 2024/358, which supplements Regulation (EU) 2020/1503 of the European Parliament and of the Council, provides a description of the credit rating methodology
used to calculate project ratings. If the calculation is based on unaudited financial statements, this will be clearly stated in the methodology description.
Monitoring
The promoter must justify the use of the funds in each of the applications. The use of the funds by the promoter will be monitored by a company external to wecity.
Compliance with Regulation (EU) 2020/1503 🇪🇺
Risk warning
Investing in this crowdfunding project involves risks, including the risk of partial or total loss of the money invested. Your investment is not covered by the deposit guarantee schemes established in accordance with Directive 2014/49/EU of the European Parliament and of the Council (*). Your investment is not covered by the investor compensation schemes established in accordance with Directive 97/9/EC of the European Parliament and of the Council (**). You may not get any return on your investment. This is not a savings product and you are advised not to invest more than 10% of your net wealth in crowdfunding projects. You may not be able to sell the investment instruments whenever you want. Even if you can assign them, you could suffer losses.
Pre-contractual cooling-off period for inexperienced investors
Inexperienced investors have a cooling-off period of four (4) days during which they can, at any time, revoke or withdraw, at any time, from their investment offer or expression of interest in the participatory financing offer without having to justify their decision and without incurring a penalty. The cooling-off period begins at the moment when the potential inexperienced investor makes an investment offer or expresses interest and expires four calendar days from that date. To exercise their right of revocation, Investors may send an email to the following address: reclamaciones@wecity.io, filling in the “subject” field of the email as follows: “REVOCATION – Name of the Opportunity – Full name of the Investor”. In the event that a monetary contribution has been made in connection with the financing offer, this amount will be returned as soon as possible to the wallet that, as an investor/user of the ‘WECITY’ Platform, has been opened in the Payment Institution ‘LEMONWAY’.
Credit risk
Credit risk is defined as the loss that may occur in the event of non-payment by the counterparty in a financial transaction. In this specific case, the risk that the Promoter will not pay the principal and/or interest of the Loan.
Sector risk Risks inherent to the specific sector.
These risks may be caused, for example, by a change in macroeconomic circumstances, a reduction in demand in the sector in which the participatory financing project operates and dependencies on other sectors. In any case, the investor must bear in mind that adverse economic conditions or cyclical changes may lead to a weakening of the Promoter’s ability to meet its financial commitments in relation to the loan.
Risk of default
The risk that the project developer may be subject to insolvency proceedings and other events affecting the project or the project developer that result in the loss of the investment for the investors. These risks may be caused by a variety of factors, including, but not limited to: (serious) change in macroeconomic circumstances, mismanagement, lack of experience, fraud, financing not fitting with the corporate purpose, failure in the product launch or lack of liquidity. In the event of the Promoter’s bankruptcy, the holders of the credits will be considered as credits with special privilege, as they are secured by a mortgage guarantee, in accordance with the cataloguing and order of priority of credits established by Royal Legislative Decree 1/2020, of May 5, which approves the revised text of the Bankruptcy Law (hereinafter, the “Bankruptcy Law”), except for those amounts that, in accordance with Article 272 of the Bankruptcy Law, should be classified either as ordinary credit or as subordinated credit, as appropriate.
Risk of lower or delayed return
The risk that the return will be lower than expected or that the project will default on the payment of principal or interest.
Risk of illiquidity of the investment
The risk that investors will not be able to sell their investment. There is no active trading market for the loan, so it is possible that the investor will not be able to find a third party to whom to assign the loan.
Other risks
Risks that are, among others, beyond the control of the project developer, such as political or regulatory risks.
You must login or be registered to view this section
You must login or be registered to view this section
You must login or be registered to view this section
You must login or be registered to view this section
You must login or be registered to view this section