

Description
wecity complies with the provisions of Regulation (EU) 2020/1503 of the European Parliament and of the Council of 7 October 2020 on European providers of participative financing services for companies and Title V of Law 5/2015 on the promotion of business financing as amended by Law 18/2022 of 28 September on the creation and growth of companies. It is authorized by the CNMV as a Participatory Financing Service Provider, registered under number 9, with a favorable proposal from the Bank of Spain.
Investor, before making your investment, please read the basic information for the investor client, as well as the pre-contractual cooling-off period for inexperienced investors .
Skin in the game: “In accordance with Article 8.2 of Regulation (EU) 2020/1503 of the European Parliament and of the Council of October 7, 2020, on European crowdfunding providers, we hereby inform you that partners, executives, and employees of wecity may invest on this occasion. These investments will be made under the same conditions as those of other investors, without receiving preferential treatment or privileged access to information.”
The investment
- Type: Fixed-rate mortgage loan
- Purpose of the loan: Purchase of an asset.
- Collateral:1st degree mortgage.
- Term: 18 months (+6 months possible extension).
- Required compliance: 6 months.
- Interest rate: 11% per year.
- Estimated total return: 16.50%
- Interest payment: at maturity.
- Current Appraisal Value: 1,530,000 € | LTV: 65 . 36 %
- HET Appraisal: €5,779,000 | LTV: 17 . 30 %
- Rating:
- Contributions:
- Developer: €650,000.00
- wecity loan: 1.000.000,00 €
- Buyers: €2,500,000
- Minimum investment: 500 €
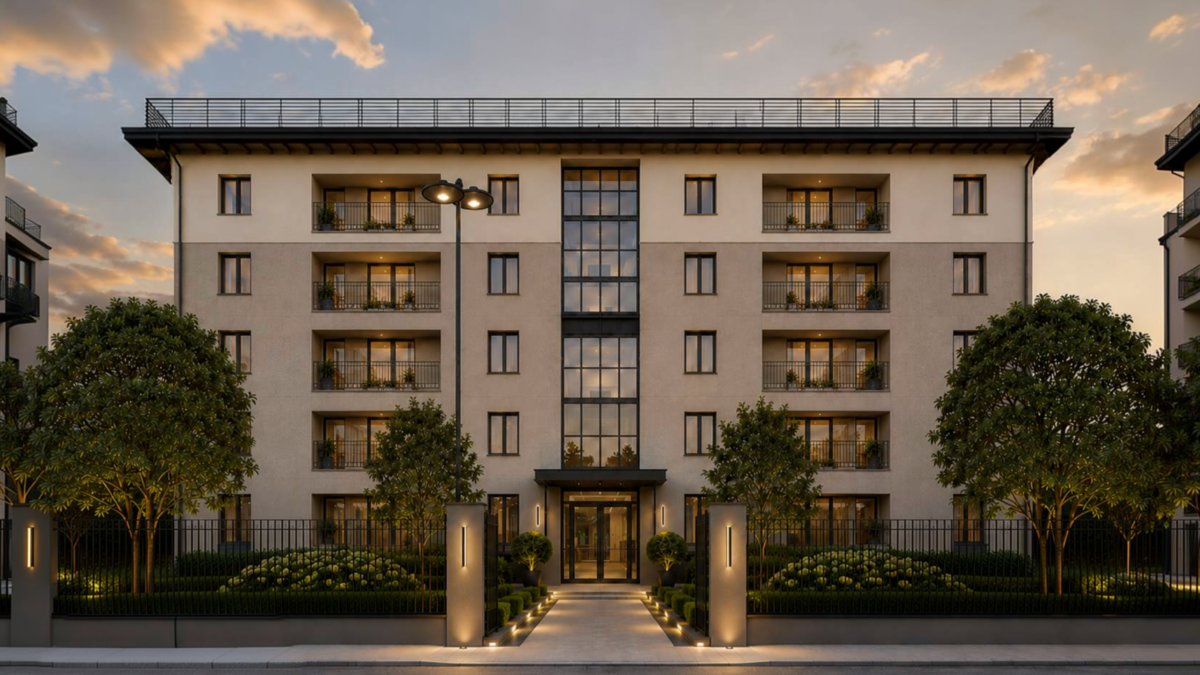
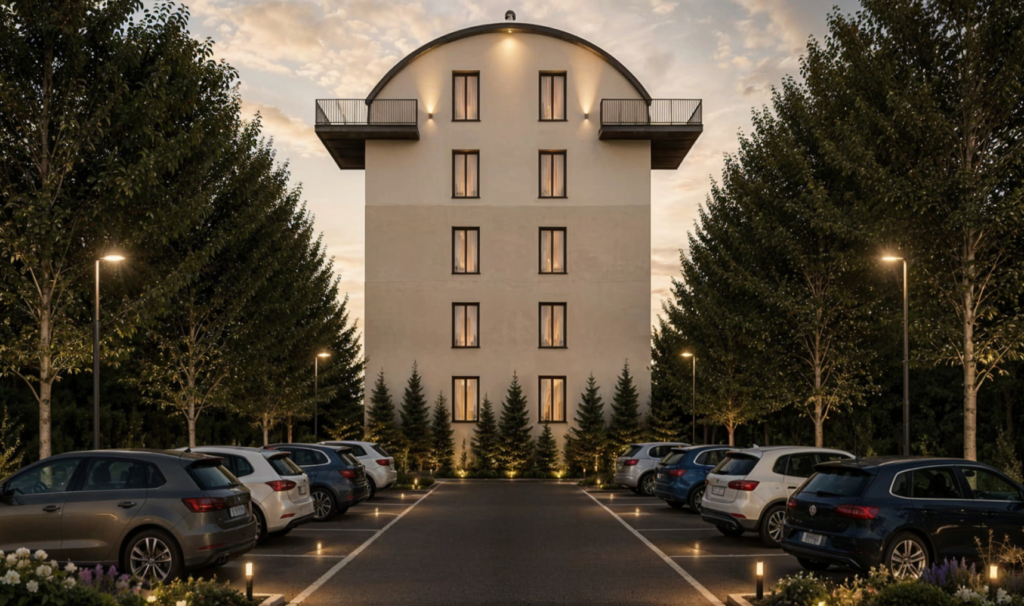
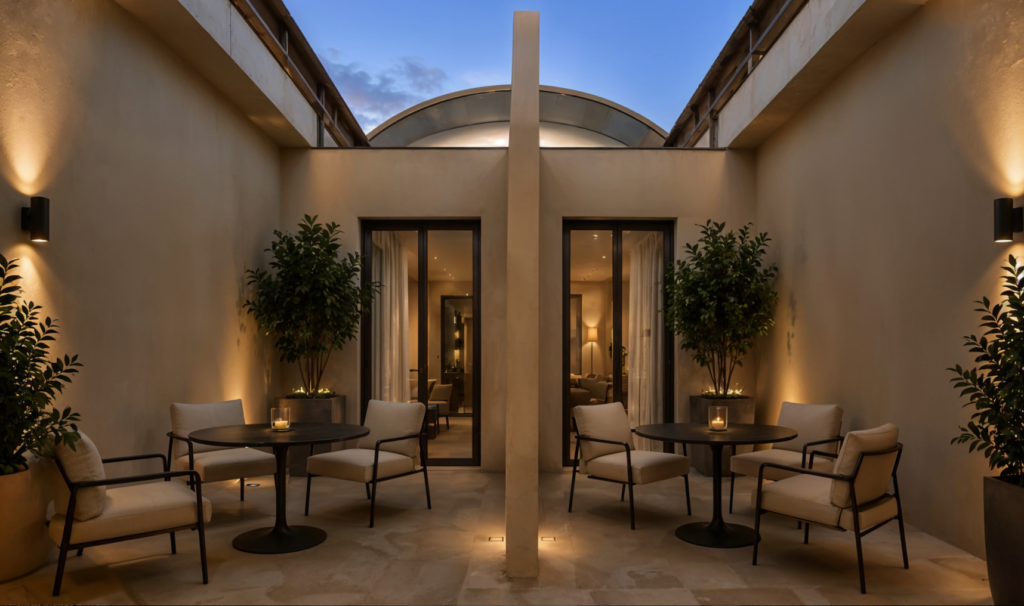
The developer Sesto Costruzioni srl is seeking financing through wecity to purchase a hotel, renovate it, and convert it into a residential building located at Via di Prato 62 (Calenzano, Florence, Italy), where 22 apartments and 44 uncovered parking spaces will be developed.
The building has a total floor area of 2,500 m². From a zoning perspective, the permit will be applied for once the property is acquired. From a commercial standpoint, sales of the units have not yet begun.
The project will be financed through a fixed-rate mortgage loan at 11% in the amount of €1,000,000, secured by a mortgage on 1first priority on the asset and will have a standard term of 18 months plus a possible 6-month extension.
The developer will contribute €650,000 in equity toward the purchase of the property, representing 15.7% of the total funds required for the project’s development. The project will be developed on a self-development basis: once the permit is obtained, buyers will purchase the units in their unfinished state and sign a construction contract with the developer to finance the construction work.
Investors are expected to exit the project upon the sale of the homes.
AInvest
AInvest does not apply in this case.
The Project
Location and Surroundings
Mortgage collateral
The loan will be secured by afirst-priority mortgage on the property, located at Via di Prato 62, Calenzano, Italy.
According to the appraisal report prepared by RYZE, the Current Appraised Value is €1,530,000 and the Appraised Value Upon Completion(HET) is €5,779,000. The loan to be granted to the developer is €1,000,000.00, representing a Loan-to-Value (LTV) ratio of 17.30% based on the HET .
Collateral Agent
The creation, maintenance, management, administration, and, where applicable, enforcement of the security interest on behalf of wecity investors will be handled by an entity external to wecity.
In this case, the designated Collateral Agent will be the one specified in the loan agreement.
Rating
wecity, as a provider of participatory financing services and in compliance with Delegated Regulation (EU) 2024/358, which supplements Regulation (EU) 2020/1503 of the European Parliament and of the Council, provides a description of the credit rating method
used to calculate project ratings. If the calculation is based on unaudited financial statements, this will be clearly stated in the method description.
Monitoring
The promoter must justify the use of the funds in each of the applications. The use of the funds by the promoter will be monitored by a company external to wecity.
Compliance with Regulation (EU) 2020/1503 🇪🇺
Risk warning
Investing in this crowdfunding project involves risks, including the risk of partial or total loss of the money invested. Your investment is not covered by the deposit guarantee schemes established in accordance with Directive 2014/49/EU of the European Parliament and of the Council (*). Your investment is not covered by the investor compensation schemes established in accordance with Directive 97/9/EC of the European Parliament and of the Council (**). You may not get any return on your investment. This is not a savings product and you are advised not to invest more than 10% of your net wealth in crowdfunding projects. You may not be able to sell the investment instruments whenever you want. Even if you can assign them, you could suffer losses.
Pre-contractual cooling-off period for inexperienced investors
Inexperienced investors have a cooling-off period of four (4) days during which they can, at any time, revoke or withdraw, at any time, from their investment offer or expression of interest in the participatory financing offer without having to justify their decision and without incurring a penalty. The cooling-off period begins at the moment when the potential inexperienced investor makes an investment offer or expresses interest and expires four calendar days from that date. To exercise their right of revocation, Investors may send an email to the following address: reclamaciones@wecity.io, filling in the “subject” field of the email as follows: “REVOCATION – Name of the Opportunity – Full name of the Investor”. In the event that a monetary contribution has been made in connection with the financing offer, this amount will be returned as soon as possible to the wallet that, as an investor/user of the ‘WECITY’ Platform, has been opened in the Payment Institution ‘LEMONWAY’.
Credit risk
Credit risk is defined as the loss that may occur in the event of non-payment by the counterparty in a financial transaction. In this specific case, the risk that the Promoter will not pay the principal and/or interest of the Loan.
Sector risk Risks inherent to the specific sector.
These risks may be caused, for example, by a change in macroeconomic circumstances, a reduction in demand in the sector in which the participatory financing project operates and dependencies on other sectors. In any case, the investor must bear in mind that adverse economic conditions or cyclical changes may lead to a weakening of the Promoter’s ability to meet its financial commitments in relation to the loan.
Risk of default
The risk that the project developer may be subject to insolvency proceedings and other events affecting the project or the project developer that result in the loss of the investment for the investors. These risks may be caused by a variety of factors, including, but not limited to: (serious) change in macroeconomic circumstances, mismanagement, lack of experience, fraud, financing not fitting with the corporate purpose, failure in the product launch or lack of liquidity. In the event of the Promoter’s bankruptcy, the holders of the credits will be considered as credits with special privilege, as they are secured by a mortgage guarantee, in accordance with the cataloguing and order of priority of credits established by Royal Legislative Decree 1/2020, of May 5, which approves the revised text of the Bankruptcy Law (hereinafter, the “Bankruptcy Law”), except for those amounts that, in accordance with Article 272 of the Bankruptcy Law, should be classified either as ordinary credit or as subordinated credit, as appropriate.
Risk of lower or delayed return
The risk that the return will be lower than expected or that the project will default on the payment of principal or interest.
Risk of illiquidity of the investment
The risk that investors will not be able to sell their investment. There is no active trading market for the loan, so it is possible that the investor will not be able to find a third party to whom to assign the loan.
Other risks
Risks that are, among others, beyond the control of the project developer, such as political or regulatory risks.
You must login or be registered to view this section
You must login or be registered to view this section
You must login or be registered to view this section
You must login or be registered to view this section
You must login or be registered to view this section